COLUMN: Waarom impactbeleggen de beurs nodig heeft
in Externe publicatie door Jori ArtsInstitutionele beleggers zoeken impact vooral in private markten. Maar om echt op te schalen, zijn de honderden biljoenen op de beurs onmisbaar
Institutionele beleggers zoeken impact vooral in private markten. Maar om echt op te schalen, zijn de honderden biljoenen op de beurs onmisbaar
a google translate of 'waarom impact beleggen de beurs nodig heeft', a column for Financial Investigator.

Using a global sample of 740 open-ended equity funds that added an ESG-related term to their name between 2016 and 2022, the study examines investor flows, portfolio ESG characteristics and fees, finding that renamed funds on average meaningfully improve their ESG profile, while flow-driven incentives and fee increases are more limited than previously thought.
Using 14,261 cyber incidents across nearly two decades (2005–2023), we provide an empirical study of cyber vulnerability among publicly-traded U.S. firms, drawing on a rich dataset of publicly observable indicators: financial data, SSL certificate records, bug bounty programs, cyber-hygiene indicators from regulatory filings, executive and governance data, and detailed incident records.
Using backtests on a comprehensive global equity dataset covering 47 countries over 1985–2023, we analyze how portfolio performance varies with the number of stocks. Two main findings stand out. First, contrary to commonly cited evidence, portfolios of 30–40 stocks are not sufficient to fully diversify idiosyncratic risk.
Second, we identify a novel dimension of concentration risk, which we refer to as FOMO (fear of missing out). When portfolios are more concentrated, stock selection becomes critical for performance, and investors face a wide dispersion in outcomes depending on which stocks are included. Investors may thus experience regret about their portfolio choice ex post when other choices would have yielded better performance. This effect is economically large and persists even for portfolios with hundreds of stocks.
Een onderzoek naar vastgoedbeleggingsstrategieën van 42 Nederlandse pensioenfondsen over de periode 2005-2024
We zijn gewend om over oorlog na te denken in termen van militaire macht en fysiek geweld. Het boek Chokepoints van Edward Fishman (2022) staat echter stil bij een nieuwe zeer ingrijpende vorm van oorlog: economische oorlogsvoering. Daarbij kan gedacht worden aan sancties, exportcontroles en financiële restricties.
Beleggen is goedkoper geworden dan ooit. Dat merk ik in mijn dagelijkse praktijk als beleggingsprofessional. Wat vroeger het exclusieve domein was van institutionele beleggers en private banks, zoals wereldwijde spreiding en blootstelling aan vrijwel elk activaklassen, is vandaag binnen handbereik van iedere particuliere belegger. De opkomst van een oneindige hoeveelheid goedkope indextrackers heeft het beleggingslandschap ingrijpend veranderd. En daarmee rijst bij mij de vraag: wat levert aanvullende beleggingsdienstverlening nog op?
Historisch gezien werd het ritme van handel en economie bepaald door zogeheten “quarter days”. In Engeland waren dat Lady Day (25 maart), Midsummer Day (24 juni), Michaelmas (29 september) en Kerstmis (25 december). Voor landeigenaren waren dit momenten van inkomsten, maar voor schuldenaren vooral dagen van afrekening. De grimmige lading van deze dagen is inmiddels verdwenen, maar een zekere spanning rond “het kwartaal” is gebleven zeker voor bestuurders die hun resultaten moeten presenteren.
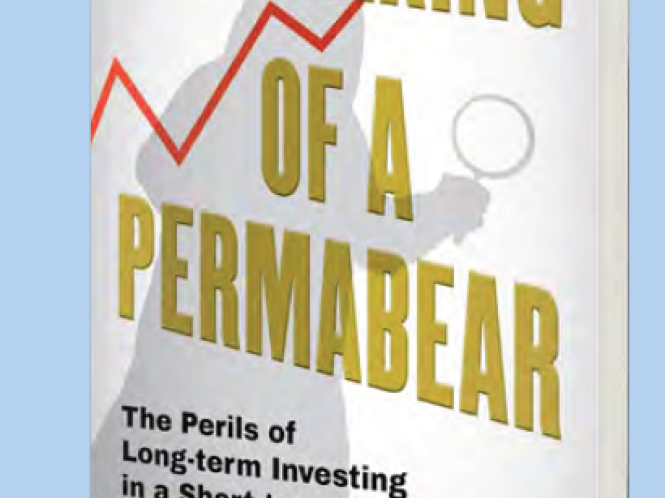
Jeremy Grantham, alongside co-author and financial historian Edward Chancellor, published his memoir in early 2026. In this volume, he reflects upon six decades in financial markets. Grantham is highly regarded as investor, and environmental philanthropist and propogandist. The book provides a comprehensive overview of his career, spent largely at GMO which he co-founded, portraying him as a long-term, fundamental value oriented and outspoken investor. It offers countless historical insights relevant to seasoned investors and analysts. This is also true for young investors who might mistakenly assume that financial and economic history or the perspectives of an ‘old Englishmen’ offer little value in today’s fast-changing, digital and AI-dominated investment landscape.
Institutional investors have historically allocated to private markets to enhance returns, generate income, and diversify portfolios. As these asset classes become increasingly accessible to private investors, the focus for Benelux wealth channels shifts beyond access to institutionalization: replicating the governance, liquidity discipline, valuation rigor, reporting transparency, and alignment standards that institutional allocators treat as non-negotiable. This article is written primarily for wealth allocators, private banks, family offices, CIOs, and distribution platforms evaluating semi-liquid private market solutions for client portfolios. It outlines a practical underwriting and governance framework designed to align investor expectations with the structural realities of private assets.
Ion Lucas Saru obtained his PhD from the Vrije Universiteit Amsterdam and is currently Energy Analyst at Northpool. In his research, he uses modern econometric tools to understand how information and trading behavior shape prices in financial markets. In two of his papers, he studies how the interaction between news and value traders affects market outcomes and how trading unrelated to new information can still move prices.
De klassieke benadering van Lifecycle-beleggen is vaak te smal. Er wordt vooral naar leeftijd en risicoprofiel gekeken, terwijl de totale economische positie van een belegger veel breder is. Arbeidsinkomen, pensioenrechten, woningvermogen, hypotheekschuld en andere mogelijke schulden bepalen immers mede het totale financiële plaatje. De vraag is dus niet alleen hoeveel risico iemand in alleen de lifecycle wil nemen, maar ook welk risico al besloten ligt in de totale balans.
Daarom is een bredere benadering nodig. In dit artikel laten wijzien hoe lifecycle-beleggen kan worden verbeterd door het te combineren met een bredere Total Portfolio Approach (TPA).